

InnoFund Ireland · R&D Capital Allowances
Irish R&D
Capital Allowances.
Look closer.
Specialist equipment, pilot lines and research facilities represent a serious investment. InnoFund Ireland helps you identify the appropriate capital allowances and any eligible R&D Tax Credit, connecting what you bought to how it is used.
- schedule30-minute first conversation
- location_onIrish-led advice
- groupsTechnical and financial expertise
Irish expertise. One connected team.
Local knowledge.
People you can rely on.
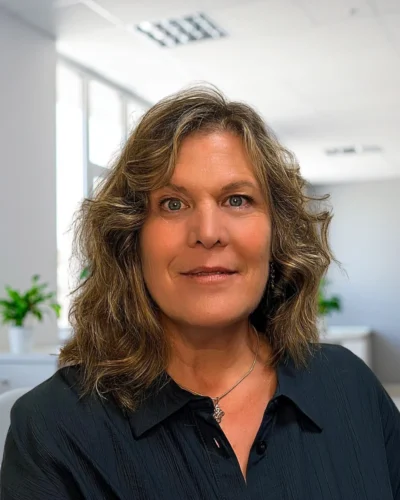
Led by Kirsten Winsryg, our team brings together Irish tax, grant, financial and technical expertise to support businesses throughout Ireland.
For Irish companies investing in innovation
The asset register
is only the beginning.
A broad description such as “laboratory fit-out” or “production equipment” rarely provides enough detail to assess a tax claim. Individual assets, installation costs, funding and actual use can point to different treatments.
We bring the technical purpose and financial record together. Your team explains the investment; we examine the available Irish reliefs and prepare a supported analysis for your accountant, without assuming every item is R&D expenditure.
- Start with the investment
- Tell us what was purchased or built, when it was brought into use and what it does.
- Use the records you have
- Asset registers, invoices, specifications and project records help us scope the review.
- See the reliefs together
- We consider the allowances, R&D credit and grant interactions rather than adding headline percentages.
- Know the next step
- We agree the information required, technical input, deliverables and fee basis before starting.
Why InnoFund
The right classification.
The right claim.
A capital expenditure review needs to understand the asset as well as the accounts. We examine entitlement, business use and tax treatment together.
Technical purpose
Understand the equipment.
Identify what the asset does, the projects it supports and whether its use changes between research and production.
Cost analysis
Unpack the investment.
Examine invoices, specifications and contractor breakdowns to separate the relevant expenditure.
Irish tax treatment
Select the appropriate relief.
Consider the asset category, ownership, timing and interaction between allowances and the R&D credit.
Evidence and reporting
Make the position usable.
Provide a clear analysis that your accountant can reconcile with the asset register and tax computation.
A deduction is not a cash credit. Capital allowances reduce taxable profits. The R&D Corporation Tax Credit has separate eligibility and payment rules. We explain the benefit and timing of each applicable treatment.
Where a specialist review can help
Equipment, facilities
and the work they enable.
These investments can warrant a closer look. Qualification depends on the specific asset, your entitlement and its business or research use.
Laboratory and testing equipment
Instruments used for experiments, measurement, validation and analysis.
Pilot lines and manufacturing plant
Equipment used to develop or test a process before or alongside commercial production.
Prototyping systems
Tools, rigs and machinery used to investigate designs, tolerances and performance.
Computer and development hardware
Equipment supporting software, data processing, engineering and technical development.
Research facilities
Construction or refurbishment of laboratories and other premises used in qualifying research.
Mixed-use assets
Equipment shared between R&D and routine operations, where the uses can be explained and evidenced.
Irish capital allowances and R&D relief
Different routes.
One coordinated review.
Irish plant and machinery allowances are generally 12.5% a year over eight years. Most qualifying industrial buildings receive 4% a year over 25 years. These are deductions from profits, not equivalent cash savings, and eligibility is asset-specific.
Eligible plant and machinery may also enter an R&D Tax Credit claim. Expenditure qualifying under the separate section 765 scientific-research allowance is excluded from that credit. We check the interaction before recommending a treatment.
Irish guidance checked 6 September 2026: Revenue: capital allowances · Revenue: R&D capital expenditure. The applicable period, facts and scheme conditions must be checked for your business.
- inventory_2
Plant and machinery
Establish the asset category, qualifying cost, ownership and date it entered business use.
- domain
Industrial buildings
Check the qualifying use and expenditure; not every commercial building falls within the industrial-buildings rules.
- experiment
The R&D proportion
Document a reasonable allocation where equipment serves both qualifying R&D and other operations.
- architecture
R&D building expenditure
The separate credit requires at least 35% qualifying R&D use over the relevant four-year period, with further conditions and potential clawback.
- eco
Accelerated allowances
Certain approved energy-efficient equipment may qualify for accelerated treatment. Eligibility needs checking against the specific scheme.
- account_balance_wallet
Funding and previous claims
Review grants, contributions and allowances already claimed to avoid unsupported overlap or duplicated relief.
How we work
From the asset
to a supported tax schedule.
We organise the review around the investment and the records available, keeping technical requests focused and the financial analysis transparent.
- 01
Scope the spend
Establish the investment, accounting periods, ownership, business use and existing claims.
- 02
Review the records
Examine invoices, the asset register, specifications and available project documentation.
- 03
Understand the use
Discuss how the equipment or facilities operate and assess any research-use allocation.
- 04
Analyse the treatment
Review the relevant Irish allowances, credit eligibility and funding interactions.
- 05
Report and coordinate
Prepare the supporting schedules and explain the position to your accountant, with follow-up responsibilities agreed.
Advice around the investment lifecycle
Before you spend.
After you invest.
Bring us in while the project is being planned or ask for a review of expenditure already incurred. The available options depend on timing, evidence and the tax position.
Planning
New equipment and facilities
Consider the records and technical detail worth retaining before procurement and construction progress.
During delivery
Cost and evidence organisation
Separate relevant project costs and record how the assets will be used.
Existing investment
Review a current position
Examine the allowances and any R&D credit already considered, without presuming further relief is available.
Ongoing use
Changes and follow-up
Consider disposals, changes of use and Revenue questions within an agreed support scope.

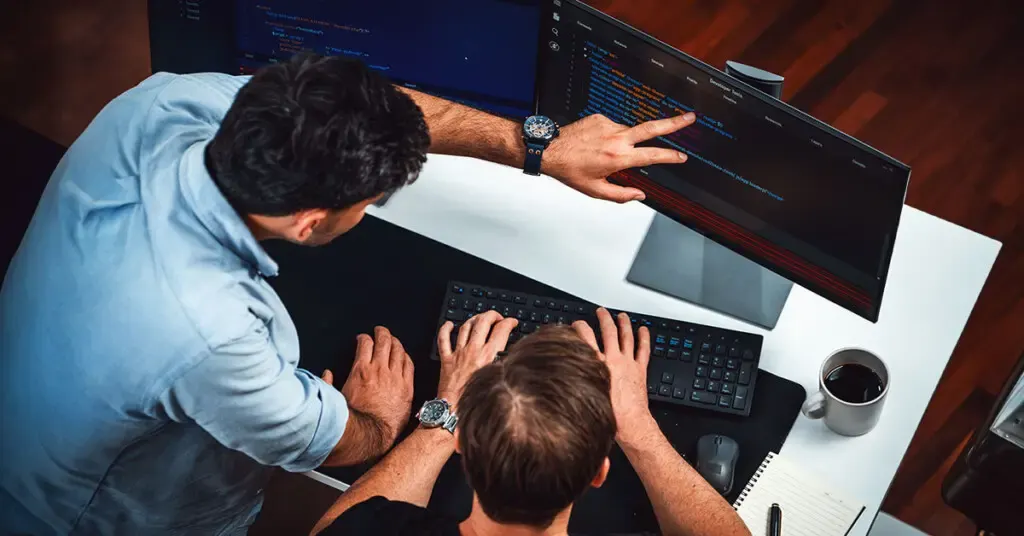
Connect the equipment to the evidence
Show what it cost.
Explain what it does.
A purchase invoice can prove expenditure without explaining its role in R&D. Technical specifications, commissioning records, usage logs and project notes help complete that picture.
We bring those records together with the grant agreements and previous tax schedules. Where the wider project also warrants an Irish R&D Tax Credit assessment, the financial and technical work can be coordinated from the outset.
- receipt_longCosts reconciled to source records
- precision_manufacturingAsset use explained by the technical team
- fact_checkReliefs considered without double-counting
The people behind our Irish service
Financial detail. Technical understanding.
Kirsten leads our Irish service, supported by a team with Irish tax, capital expenditure, engineering and science expertise. We work with your accountant to assess the assets, understand their role in your R&D and identify the Irish reliefs that may apply.



Connected support in Ireland
See the wider
innovation opportunity.
Different reliefs answer different questions. Our Ireland team helps you consider the appropriate services together, with a clear distinction between expenditure, funding and qualifying profits.
R&D Tax Credit
Identify qualifying development work and prepare an evidence-led Irish claim.
Knowledge Development Box
Assess eligible profits from qualifying software and other developed IP.
Innovation Grants
Assess relevant funding routes and prepare a credible application.
Claim Review & Revenue Support
Review a claim or coordinate an evidence-backed response to Revenue.
Your Irish service questions
Questions before you start.
A first conversation can clarify the position for your Irish business, the information needed and the right next step.
Book a consultation arrow_outwardIs this the same as an R&D Tax Credit claim? add
No. Capital allowances concern deductions for qualifying capital expenditure; the Irish R&D Tax Credit is a separate relief. We assess where each may apply and where the rules prevent an overlap.
Can an asset receive allowances and an R&D credit? add
Potentially. Ordinary plant and machinery allowances and the R&D credit can apply to eligible expenditure, subject to their respective conditions. The separate section 765 scientific-research allowance cannot simply be stacked with the credit.
Does equipment need to be used only for R&D? add
Not necessarily. Mixed research and operational use needs a supported allocation for the R&D claim. We examine how the asset is used and the evidence available, rather than applying a standard percentage to every item.
Does every laboratory building qualify? add
No. Building expenditure needs its own review. For the R&D building credit, the qualifying-use threshold is only one condition; the expenditure, timing, company activity and subsequent use also matter.
Can we review equipment that our accountant has already considered? add
Yes. We can review the scope, classification and supporting use analysis alongside your accountant. The result may confirm the existing treatment, identify further work or show that an alternative approach is appropriate.
Do grants change the calculation? add
They can. We examine the award terms, the expenditure funded and the relevant tax relief rules before preparing the calculation. Bring the grant agreements as well as the asset invoices.
What records should we prepare? add
Start with your asset register, invoices, specifications, expenditure dates and a short description of the equipment’s use. For facilities, construction records and plans may help. We then provide a focused request for any further information.
Will you work with our existing accountant? add
Yes. We provide specialist asset and R&D analysis while your accountant retains the wider tax relationship. Filing responsibilities, deadlines and follow-up support are agreed before the engagement starts.
Your next step
Make the most
of a closer look.
Bring the investment type, approximate spend, dates and any existing claim. Our Ireland team will help identify the questions that matter and whether a detailed review is worthwhile.
- schedule30 minutesA focused first conversation
- verifiedExpert guidanceTechnical, tax and commercial context
- handshakeCommitment freeA clear next step, without obligation