Sector expertise
R&D Tax Credits for Biotechnology Companies
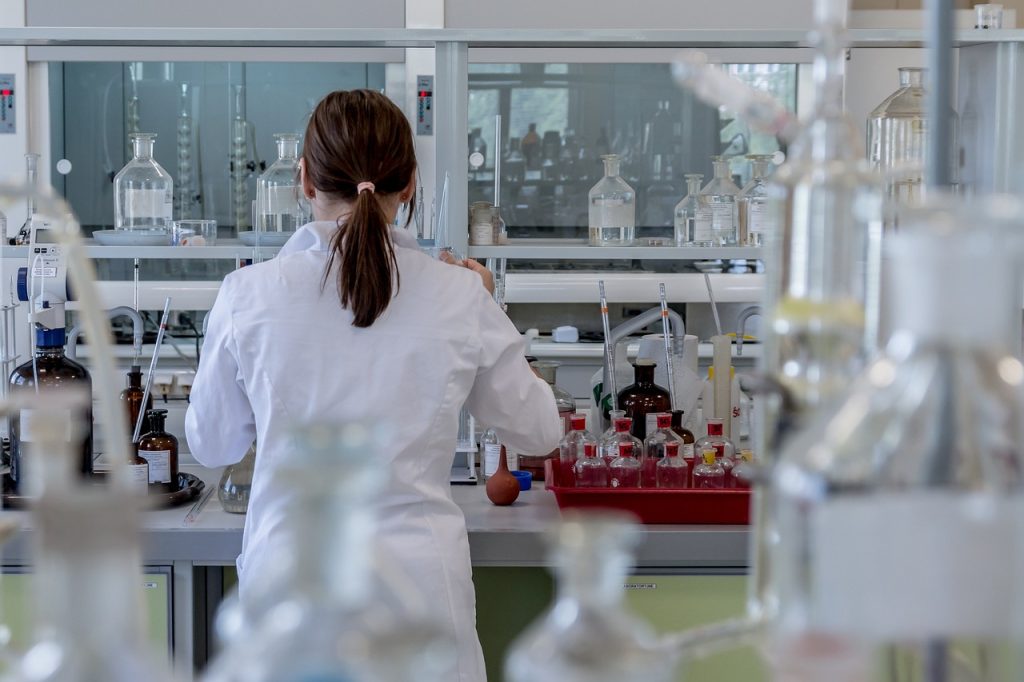
Biotechnology companies use biological systems to develop new products, processes, diagnostics and production methods. Scientific uncertainty is central to much of this work, from assay and strain development to fermentation, bioinformatics, protein engineering and scale-up.
Innovation in biotechnology
Biotechnology businesses solve technical problems every day.
Biotechnology R&D is evidence-led and iterative. Biological variability, incomplete knowledge and scale effects mean competent professionals often need to design experiments and refine methods before a reliable outcome is possible.
This includes work across:
- Assay development
- Genetic engineering
- Bioprocess development
- Diagnostics
- Fermentation
- Bioinformatics
- Protein engineering
- Cell culture
- Biomaterials
- Process scale-up
- Stability and storage
- Environmental biotechnology
Qualifying R&D may arise where a business is not simply applying known methods, but is testing, adapting or developing a new approach because the scientific or technological answer is uncertain.
Explore our R&D tax relief service for help assessing your biotechnology projects and preparing a claim.
A note from Dr Jack Brent
Biotechnology R&D claims need clear technical evidence.
Biotechnology projects can look like routine commercial delivery from the outside, even when the team has worked through difficult scientific or technological uncertainty. A defensible claim must identify the advance sought, the available baseline and why a competent professional could not readily determine the solution.
InnoFund separates ordinary delivery from the qualifying work and connects the technical narrative to contemporaneous evidence and eligible expenditure. That produces a focused claim that can withstand HMRC scrutiny.

Dr Jack Brent
Senior R&D Tax Manager
- PhD in Materials Science and MChem in Chemistry.
- ATT qualified with detailed knowledge of the UK R&D tax regime.
- Research experience across advanced materials, battery technology and solar energy harvesting.
Client experience
Biotechnology Companies Recommend InnoFund
Practical support from a multidisciplinary team that understands both the technical work and the claim.
Clear boundaries
Not every biotechnology project qualifies.
Commercial value, novelty or project difficulty do not qualify a project on their own. Examples of work that may fall outside the scheme include:
- Routine delivery using established methods
- Standard installation or configuration
- Ordinary maintenance and repair
- Commercial or cosmetic changes
- Routine quality control
- Straightforward replication of an existing solution
- General project management
- Work completed after technical uncertainty was resolved
Many projects contain a mixture of qualifying and non-qualifying activity. InnoFund identifies the technical boundary so the claim remains accurate and proportionate.
Eligible expenditure
Eligible R&D costs for biotechnology businesses.
Costs directly connected to qualifying activity may include:
- Staff time spent on qualifying R&D
- Employer National Insurance and pension contributions
- Subcontracted R&D, where eligible
- Externally provided workers
- Software, cloud computing and data costs used for R&D
- Materials and consumables used in trials
- Prototype components and testing costs
- Technical consultancy, where eligible
We trace expenditure back to the qualifying work and apply the rules relevant to the company, contract and accounting period.
Evidence & scrutiny
HMRC risk areas for biotechnology R&D claims.
A strong claim explains the science or technology rather than relying on broad statements about innovation. Common risk areas include:
- Claiming commercial complexity rather than technical uncertainty
- No clear baseline of existing science or technology
- Routine work presented as R&D
- Weak records of trials, failures and iteration
- Incorrect treatment of subcontracted or customer-funded work
- No competent professional input
- Overclaiming whole projects instead of qualifying activity
- Unclear project and cost boundaries
InnoFund reviews both the technical position and the expenditure so each claim is clear, evidence-led and defensible.
Your next step
Don’t guess. Know for sure.
Got a project you want to discuss? InnoFund separates routine delivery from genuine R&D so claims are accurate, compliant and properly evidenced.
- 30 minutes
- Expert guidance
- Commitment free