Sector expertise
R&D Tax Credits for Chemical Companies
Chemical companies are often at the centre of technical innovation, developing new formulations, materials, coatings, compounds, processes and production methods that must perform reliably, safely and commercially. Where your business is improving chemical performance, scaling up production, reducing environmental impact or overcoming uncertainty in formulation, synthesis, testing or manufacturing, you may be carrying out qualifying R&D. InnoFund helps chemical companies identify eligible activity, prepare compliant R&D Tax Credit claims and protect future innovation funding opportunities.
Sector innovation
Innovation in Chemicals
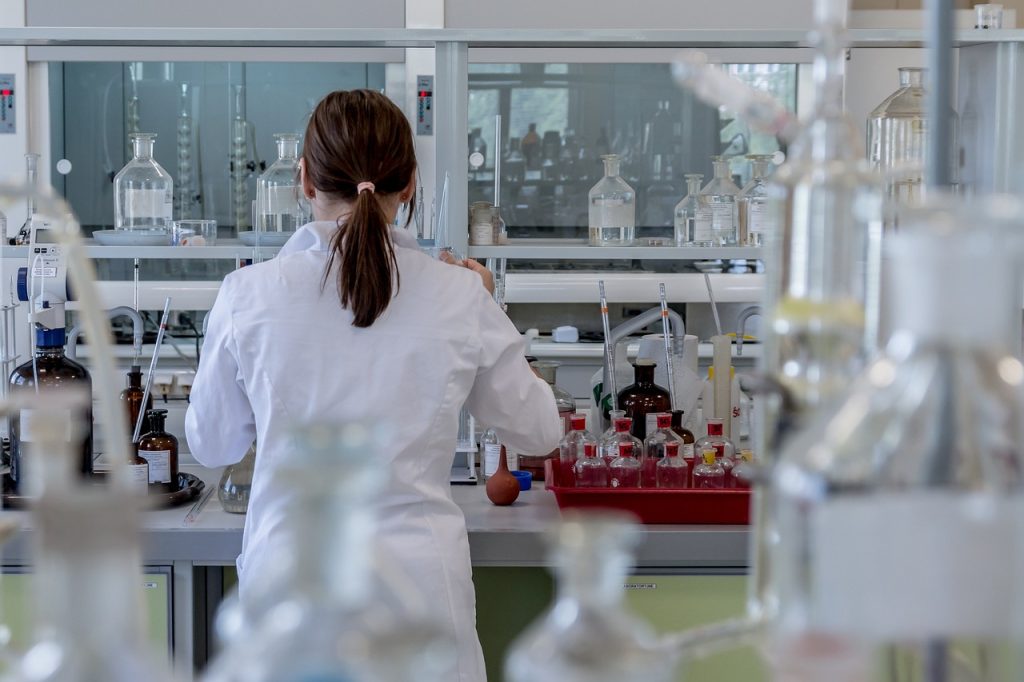
Innovation in the chemical sector often involves experimentation, testing and iteration across formulation, synthesis, materials behaviour, process control, stability, safety, compliance and scale-up. Qualifying R&D may arise where a business is developing or improving products, materials or processes because existing solutions cannot meet the required performance, cost, safety, environmental or production standards.
This includes work across:
- Chemical formulation
- Materials chemistry
- Process development
- Scale-up challenges
- Polymers and composites
- Coatings and adhesives
- Battery materials
- Sustainable chemistry
- Waste reduction
- Stability testing
- Manufacturing optimisation
- Product performance testing
Chemical R&D is often found in the detail: formulation records, lab tests, batch behaviour, process changes, scale-up issues, material properties and the iterations needed to reach a reliable technical outcome.
A note from Dr Jack Brent
Chemical R&D Claims Need Scientific Precision and Strong Evidence
Chemical R&D claims need to be grounded in the science behind the project. A business may be improving a formulation, developing a new material, changing a production process or reducing environmental impact, but HMRC will want to understand the specific scientific or technological uncertainty involved.
That uncertainty might sit in chemical stability, reactivity, purity, yield, compatibility, material performance, production scale-up, safety, degradation, environmental impact or the interaction between ingredients, processes and end-use conditions. A strong claim needs to explain what was not readily deducible at the start of the project, what testing was carried out, what failed, what changed and how the business moved towards a workable solution.
Dr Jack Brent, InnoFund's Senior R&D Tax Manager, brings a rare combination of chemistry, materials science and R&D tax expertise. With a PhD in Materials Science, an MChem in Chemistry and research experience across graphene, phosphorene, composites, nanomaterials, battery technology and solar energy harvesting, Jack helps chemical businesses present their R&D in a way that is technically accurate, commercially relevant and compliant.

Dr Jack Brent
Senior R&D Tax Manager
- PhD in Materials Science and MChem in Chemistry.
- ATT qualified with detailed knowledge of the UK R&D tax regime.
- Research experience across advanced materials, battery technology and solar energy harvesting.
Client experience
Chemicals Companies Recommend InnoFund
Practical support from a multidisciplinary team that understands both the technical work and the claim.
Clear boundaries
Not Every Chemical Project Qualifies for R&D Tax Credits.
Not every chemical formulation, product update or production issue will qualify for R&D Tax Credits. The key question is whether the business faced scientific or technological uncertainty and carried out systematic work to resolve it.
Examples of work that may not qualify include:
- Routine quality control
- Standard batch production
- Basic formulation tweaks
- Cosmetic product changes
- Routine compliance testing
- Standard ingredient substitution
- Normal manufacturing optimisation
- Off-the-shelf process changes
- Commercial product launches
- General market research
- Routine troubleshooting
- Work after uncertainty is resolved
Chemical projects often contain a mixture of qualifying and non-qualifying activity. InnoFund helps separate routine production from genuine R&D so the claim is accurate, compliant and defensible.
Eligible expenditure
Eligible R&D Costs for Chemical Businesses
Chemical businesses may be able to claim relief on qualifying costs linked to eligible R&D projects, including:
- Chemist and scientist staff time
- Process engineer staff time
- Technical director time
- Employer NIC and pension costs
- Subcontracted R&D, where eligible
- Externally provided workers
- Software used for modelling or testing
- Cloud computing and data costs
- Materials used in trials
- Prototype formulation costs
- Consumables used in R&D
- Testing and analysis costs
The treatment of trial materials, consumables, subcontracted work, testing, externally provided workers and technical consultancy can be particularly important in chemical R&D claims.
InnoFund helps identify which costs are eligible and ensures the claim is built around the qualifying scientific and technical work, not just the wider commercial project.
Evidence & scrutiny
HMRC Risk Areas for Chemical R&D Claims
HMRC is applying greater scrutiny to R&D Tax Credit claims, including claims from chemical, manufacturing and materials businesses. A strong claim must explain the scientific uncertainty clearly and show why the work went beyond routine production, quality control or commercial reformulation.
Common risk areas include:
- Routine production claimed as R&D
- Weak scientific uncertainty explanation
- No clear technical baseline
- Overclaiming quality control
- Claiming cosmetic reformulation only
- Poor records of failed trials
- Incorrect subcontractor treatment
- Not separating commercial and technical work
- No competent professional input
- Generic sustainability claims
- Unclear project boundaries
- Poor evidence of testing and iteration
InnoFund helps chemical companies prepare claims that are clear, compliant and evidence-led. We focus on the scientific work behind the project, the uncertainty faced, the process followed and the costs directly connected to qualifying activity.
Your next step
Don't guess. Know for sure.
Got a project you want to discuss? InnoFund helps separate routine delivery from genuine R&D so that claims are accurate, compliant and properly evidenced. Speak to our innovation funding experts today.
- 30 minutes
- Expert guidance
- Commitment free