

Sector expertise
R&D Tax Credits for Aerospace Companies
Developing lighter structures, more efficient propulsion or more reliable flight systems can mean working beyond established engineering solutions. Aerospace companies may qualify for R&D tax relief where a project seeks a scientific or technological advance and tackles uncertainty that a competent professional could not readily resolve.
InnoFund helps aerospace businesses identify qualifying work, assess eligible costs and prepare an evidence-led R&D Tax Credit claim.
Sector innovation
Innovation in aerospace
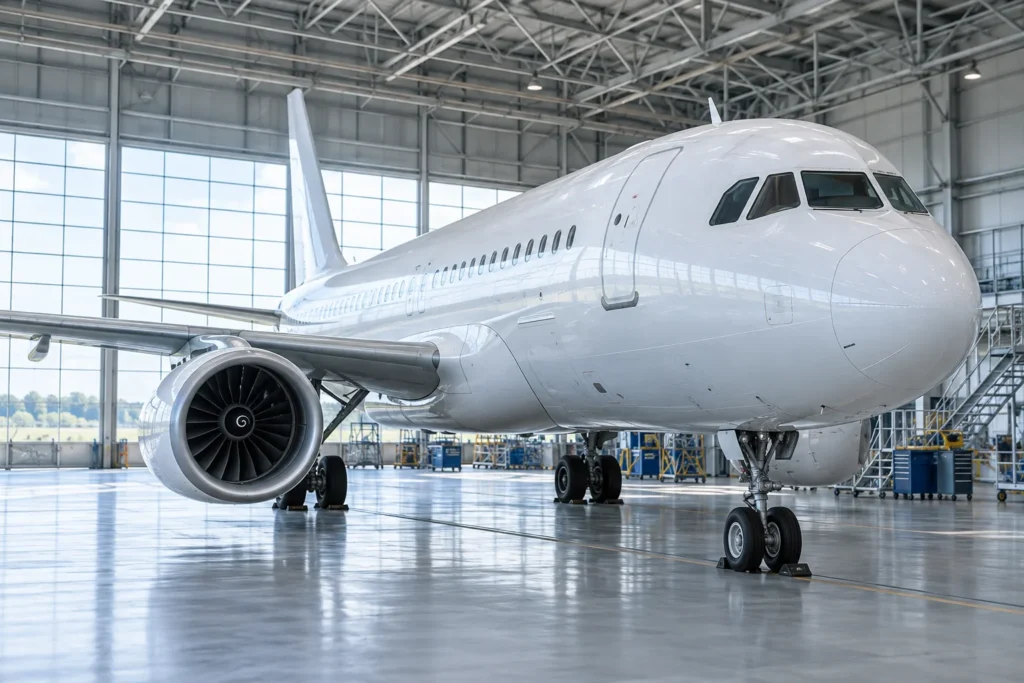
Aerospace development brings together aerodynamics, materials science, electronics, software and precision engineering. Improving one part of a system can introduce new challenges elsewhere: reducing structural weight may affect fatigue performance, while increasing electrical power can create difficult thermal-management problems. Qualifying R&D can sit within a component, production process or subsystem, as well as a complete aircraft or spacecraft.
The claim should explain the technical problem and the work undertaken to solve it. Businesses working across civil aviation and military programmes can also explore our Defence R&D Tax Credits guidance. Where the challenge concerns production methods or repeatability, our Manufacturing R&D Tax Credits page covers related activity.
- Aircraft structures and components
- Advanced composites and alloys
- Propulsion and thermal management
- Avionics and flight-control software
- Precision and additive manufacturing
- Aerodynamic modelling and testing
- Uncrewed aircraft systems
- Satellite and spacecraft technology
Specialist support
Aerospace R&D claims need clear technical boundaries
A complex aerospace programme can contain substantial routine engineering alongside qualifying R&D. A useful claim explains what existing knowledge could achieve, why that was insufficient, and what the development team did to address the remaining uncertainty.
Design reviews, prototype changes, test results and the reasoning of experienced technical staff can help establish those boundaries. The financial assessment then needs to follow the qualifying work, including a careful review of customer contracts, outsourced development and costs connected with overseas activity.
InnoFund brings technical and tax considerations together to help aerospace businesses prepare a clear, supported claim.

Simba Mareverwa
Head of Tax Compliance & HMRC Disputes
- 20+ years in corporation tax compliance, including leadership of HMRC disputes.
- Extensive experience defending UK R&D Tax Credit claims under enquiry.
- Patent Box claim and enquiry experience dating from the scheme’s introduction.
Client experience
Companies Recommend InnoFund
Practical support from a multidisciplinary team that understands both the technical work and the claim.
Clear boundaries
Not every aerospace project qualifies for R&D Tax Credits
High technical standards, certification requirements and demanding customers do not automatically make a project eligible. Work that applies established methods without resolving scientific or technological uncertainty will generally fall outside qualifying R&D.
Examples include:
- Standard component manufacture
- Routine aircraft maintenance and repair
- Established overhaul procedures
- Ordinary design customisation
- Replicating known technology
- Routine quality-control inspections
- Standard software implementation
- Procurement and bid preparation
- Certification of already-proven functionality
- Production after technical uncertainty is resolved
Where a wider programme contains qualifying development, the claim must distinguish that work from routine delivery.
Eligible expenditure
Eligible R&D costs for aerospace businesses
Depending on the work and the applicable rules, eligible expenditure may include:
- The qualifying share of engineers', scientists' and developers' employment costs
- Related employer National Insurance and pension contributions
- Eligible externally provided workers
- Qualifying payments for contracted-out R&D
- Software used in qualifying development
- Eligible data licences and cloud computing used directly in R&D
- Materials and components consumed or transformed in qualifying experiments
- Fuel, power and other consumables attributable to R&D
Costs must be allocated to qualifying activities on a supportable basis. Materials incorporated into products sold or transferred in the ordinary course of business are subject to restrictions. Equipment purchases, rent and patent costs are not ordinary qualifying expenditure under these R&D relief schemes.
Testing invoices are not a standalone eligible category: treatment depends on what was purchased, the contractual arrangement and the applicable cost rules. See HMRC's guidance on qualifying R&D costs.
Evidence & scrutiny
HMRC risk areas for aerospace R&D claims
A clear aerospace claim connects each claimed activity with the advance sought and the scientific or technological uncertainty being addressed. Particular areas to review include:
- Treating certification or safety requirements as evidence of R&D by themselves
- Describing an ambitious product without explaining the technological advance
- Including entire development programmes rather than qualifying activities
- Claiming routine production, inspection or maintenance
- Weak evidence for staff-time allocations
- Incorrect treatment of customer-funded or contracted-out work
- Including ineligible prototype or production materials
- Assuming all overseas engineering or testing costs qualify
For accounting periods beginning on or after 1 April 2024, the contracted-out R&D rules require close attention to who intended or contemplated the R&D when the contract was entered into. Exceptions and transitional rules can affect the result. Customer funding alone does not determine who can claim; HMRC's contracted-out R&D guidance explains the framework.
Restrictions also apply to certain overseas contractor and externally provided worker costs. Limited exceptions can apply where necessary conditions cannot reasonably be replicated in the UK; lower costs or the availability of workers do not, by themselves, satisfy that exception.
Your next step
Discuss your aerospace R&D project
Developing an aerospace component, process or system and unsure where the qualifying work begins? Talk to InnoFund about your technical challenges, project evidence and potential R&D tax relief.
- 30 minutes
- Expert guidance
- Commitment free